Private Wealth Management

Before you sell stock,
retire, or exit a business, build the plan.

Wealthstone helps affluent professionals, executives, and business owners make tax-aware decisions before concentrated stock sales, retirement transitions, and business exits.

3Planning disciplines,
one integrated firm
1Decision that determines
the next decade
0Products sold.
Planning first, always
Zak Gardezy, CFP®
Zak Gardezy, CFP®Founder & Managing Partner, Senior Wealth Advisor

Discover how Wealthstone’s boutique model, intentionally limited 1:100 advisor-to-household ratio, and deeper client relationships create a more personal and impactful approach to wealth management.

Choose Your Path

Three decisions. Three disciplines.

Every client arrives at Wealthstone facing one of three wealth transitions. Each has its own methodology, its own tools, and its own set of irreversible mistakes.

Concentrated Stock Planning

For

  • Public company executives and founders
  • Early employees and equity compensation recipients
  • Investors with large unrealized gains in one name

Embedded gains, trading windows, tax lock-in, and the emotional weight of a winning stock, resolved into a staged diversification plan.

Build Your Stock Diversification Plan →
High-Net-Worth Retirement Planning

For

  • Professionals within 5 to 10 years of retirement
  • Executives with complex compensation
  • Families with taxable portfolios, pensions, deferred comp, or real estate

When can I retire, how much can I spend, and how do I keep taxes from consuming the answer. Retirement planning beyond the brochure.

Build Your Retirement Blueprint →

Business Owner Retirement & Exit Planning

For

  • Owners preparing to sell or approaching liquidity
  • Entrepreneurs with most of their net worth inside the business
  • Owners weighing sale, succession, or recapitalization

What you actually keep after taxes is decided before the deal, not after it. Turn business value into personal financial independence.

Plan Before You Exit →
The Cost of Planning Too Late

These decisions are one-directional.

A stock sold in the wrong year, a conversion window left unused, an exit signed before the structure was reviewed. None of them can be undone. The cost is rarely visible until the return is filed.

23.8%+Top federal rate on long-term gains including net investment income tax, before state tax, on an unplanned single-year sale
~10 yrsThe typical corridor between retirement and required distributions where low brackets go unused without a conversion plan
$10M+Federal gain exclusion potentially available under §1202 to qualifying business sellers, and forfeited when structure is reviewed too late

Figures are illustrative and based on 2026 federal tax law. Individual outcomes depend on facts, timing, and eligibility. This is not tax advice.

Decision Gateway

What decision are you facing?

Answer one question. We will point you to the right methodology, the right tool, and the right first meeting.

Your path

Concentrated Stock Planning

Start with the Tax Exposure Calculator to see the embedded gain and what an unplanned sale would cost. Then review the 4-Stage Methodology for turning one position into a diversified balance sheet.

Your path

High-Net-Worth Retirement Planning

Take the Retirement Readiness Assessment to see where your plan stands. Then review the Retirement Blueprint, from withdrawal architecture to the Roth conversion corridor.

Your path

Business Owner Exit Planning

Start with the Exit Proceeds Calculator to see your estimated after-tax number. Then review the Exit Blueprint, from pre-sale structure to post-sale portfolio strategy.

Your path

Integrated Private Wealth Planning

Most Wealthstone clients cross more than one lane: the executive with concentrated stock approaching retirement, the owner whose exit funds it. That intersection is exactly where the firm operates. Start with a conversation.

The Wealthstone Blueprint

One discipline behind every path.

Whichever transition brings you here, the work follows the same institutional sequence. Planning first. Products never lead.

01

Map

The full balance sheet: positions, basis, entities, compensation, restrictions, and the decisions already in motion.

02

Model

The transition itself, quantified. Tax outcomes by year, risk by scenario, the cost of acting now versus staging.

03

Decide

A written plan with sequenced actions, owners, and dates. You see the trade-offs before you make them.

04

Govern

Annual bracket management, rebalancing rules, and course corrections as law, markets, and life change.

Tool · Concentrated Stock

See the tax before you sell.

Enter your position, basis, and state. The Tax Exposure Calculator shows the embedded gain, the estimated tax on a sale, and what that capital could become over 20 years if the Wealthstone Protocol potentially eliminated the tax.

Estimate Your Tax Exposure →

Tax Exposure Calculator

Position value$4,200,000
Embedded gain$3,150,000
Estimated tax on sale$907,200
Net proceeds$3,292,800

Illustrative. 20% federal LTCG + 3.8% NIIT + 5% state on full gain.

Retirement Readiness Assessment

Withdrawal architectureNot yet written
Roth conversion corridor8 years available
Sequence risk reservePartially funded
Readiness tierDeveloping
Tool · Retirement

Eight questions. An honest read on your plan.

The Retirement Readiness Assessment measures the parts of retirement most portfolios ignore: withdrawal order, conversion windows, sequence risk, and spending policy. Three minutes, no email required.

Take the Assessment →
Tool · Business Exit

Know your after-tax number first.

Most owners have never seen what they would actually keep. The Exit Proceeds Calculator models deal structure, transaction costs, QSBS eligibility, and state tax, and shows the number that has to fund everything after.

See What You Would Keep →

Exit Proceeds Calculator

Sale price$12,000,000
Taxes and transaction costs$3,180,000
Keep rate73.5%
Net proceeds$8,820,000

Illustrative stock sale, no QSBS, 5% state, 2% transaction costs.

Insights & Education

Frameworks, not headlines.

Strategic briefs written for people who will make one of these decisions this decade. No market commentary theater.

Tax Strategy

Long-short tax-loss harvesting: gains in the account, losses on the return

How institutional long-short portfolios track the index while generating harvestable losses at multiples of what direct indexing produces.

Read the article →

Retirement

The conversion corridor: the decade most plans waste

Between the last paycheck and the first RMD sits the cheapest tax you will ever pay. Most households never use it.

Read the framework →

Concentrated Stock

The Zak Gardezy 4-Stage Methodology, explained

Exchange funds, opportunity zones, direct indexing, and hedging, sequenced so each stage funds and offsets the next.

Read the article →
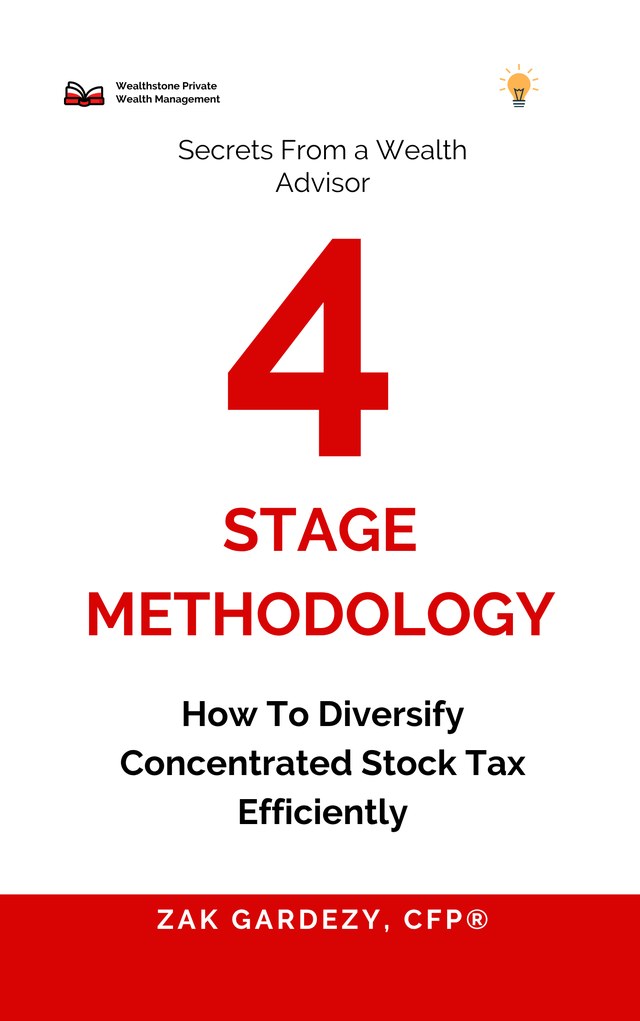
Secrets From a Wealth Advisor by Zak Gardezy, CFP® — book cover
The Book

The methodology, written down.

Secrets From a Wealth Advisor lays out the 4-Stage Methodology Wealthstone uses to diversify concentrated stock positions tax efficiently. For the executive, founder, or early employee who wants to understand the decision before delegating it.

The First Meeting

One conversation, before the decision.

A private consultation. No pitch, no products. You leave with a clearer read on the decision in front of you.